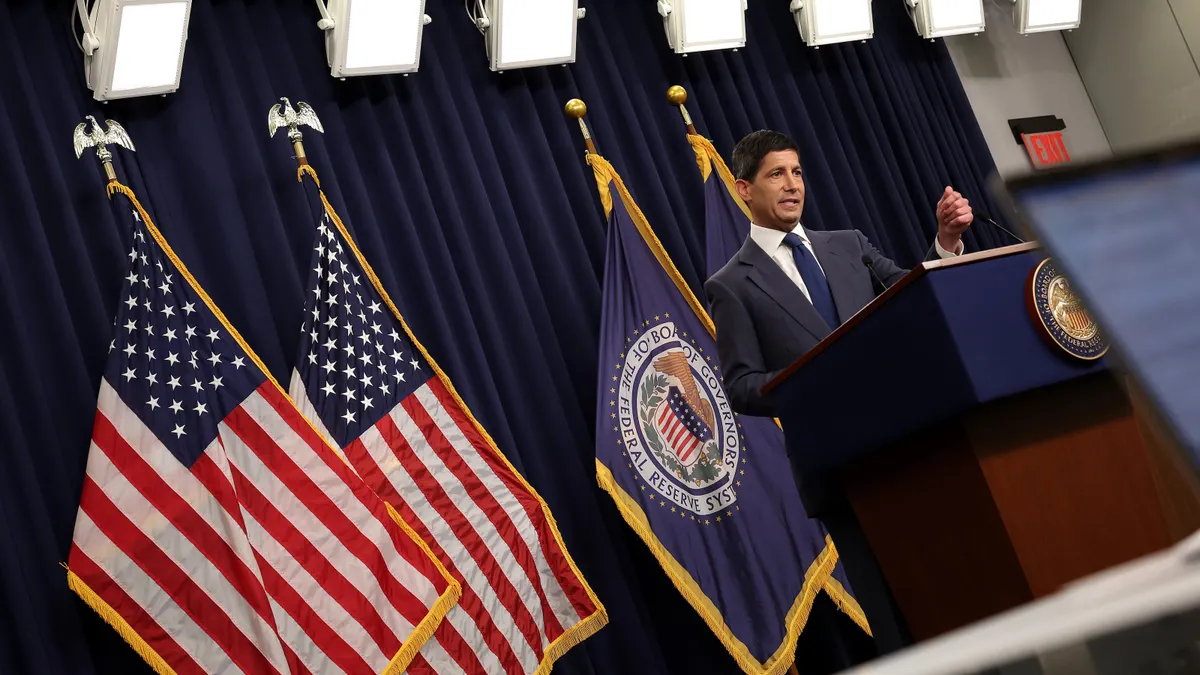
The Federal Reserve raised interest rates Wednesday, threatening to push construction projects that are barely penciling out over the financial abyss.
The central bank increased its benchmark interest rate by 25 basis points, its first hike since 2023. The move comes as inflation runs stubbornly above the Fed’s 2% target rate.
The cut will reduce the viability of some planned commercial projects, said Michael Guckes, chief economist at ConstructConnect, a Cincinnati-based commercial construction data provider.
“In the bigger picture, higher financing costs will weaken the profitability calculations of owners and developers considering new commercial real estate projects,” Guckes told Construction Dive. “Projects that were on the edge of meeting their profitability goals may now be falling short, such projects will not go to bid.”
The impact could also extend to projects already underway, Guckes added. Short-term credit and revolving loans tied to the prime rate will move higher with the Fed’s increase. That will raise borrowing costs for contractors and project owners.
“If the change in rates severely impacts the project owner, this could result in an unexpected delay in contractor payments,” said Guckes. “In a worst-case scenario, higher rates could force the owner to put the project on hold, or even abandon it, which would leave the contractor saddled with immediate expenses and accounts receivable that are difficult to recoup from the owner.”
But economists are divided on whether Wednesday’s hike will worsen borrowing conditions for construction in general.
Long-term Treasury yields influence commercial real estate financing more than the Fed’s overnight rate, said Brian Strawberry, chief economist at FMI, a Raleigh, North Carolina-based construction consulting firm. If the Fed’s move assures bond investors that inflation will come under control, longer-term rates could actually fall, he said.
“A hike would immediately raise the cost of floating-rate construction loans, which is real money on projects carrying debt, but the bigger effect is likely lower long-term rates,” Strawberry told Construction Dive. “A hike that convinces markets the Fed is serious about inflation tends to pull the 10-year [Treasury] down, and that is where construction actually borrows.”
Inflation impacts on construction costs
But taming inflation fears is easier said than done, even with the rate hike on Wednesday.
Elevated materials and labor costs already threaten project viability, said Kenneth Roberts, partner and chair of the construction law group at Venable, a Washington, D.C.-based law firm. Nonresidential construction input prices increased 8.9% year over year in August, with several major building materials posting double-digit increases.
In other words, though Wednesday’s hike may help pull down longer-term borrowing rates, rising construction costs could still keep planned projects from kicking off.
“I don’t see any data that suggests that in the next six months, the inflation that the construction industry has experienced in the last year is going to decrease,” Roberts told Construction Dive. “In fact, I think everybody is stating the opposite. That is, they think that we’re going into even a more inflationary time period.”
Strawberry sees a similar trend in the producer price data. Construction materials price escalation currently far outpaces contractors’ bid prices over the past year.
“That squeeze plus costly construction debt is thinning the pipeline of new starts,” said Strawberry. “Fewer deliveries eventually mean tighter vacancies and the next round of rent growth and building. Until then, the planning reality is a cost of capital far above the 2010s.”
Sectors with more protection
The rate increase will hit construction unevenly, said Strawberry.
Housing and private commercial development are the most sensitive to borrowing costs, he said. On the other hand, data centers and semiconductor plants, the key sectors in nonresidential construction, are much better insulated.
A majority of those projects rely on tech giants’ deep pockets or government incentives, limiting the role of borrowing costs.
“Much of that spending runs on corporate cash flow and elevated stock values, so borrowing costs barely touch it,” said Strawberry. “That mix is what keeps total spending from falling as hard as housing.”
Fed hikes come in ‘waves’
Guckes questioned whether the Wednesday increase represents a single adjustment or is just the preliminary volley in another round of tightening.
Fed rate changes have historically come in a series of moves, Guckes told Construction Dive. If that pattern holds, owners could face additional increases in borrowing costs after Wednesday.
“It’s important for business owners to realize that in the modern era, Fed rate movements have come in waves,” said Guckes. “In recent decades the Fed has not raised the Federal Funds Rate one time by 25 basis points or 50 basis points and then held at that rate for a sustained period of time. Rather, the Fed has a track record of making multiple small rate increases relatively quickly.”